
The government plans to disburse the salaries of civil servants (ASN) and retirees through Village Cooperatives/Red and White Village Cooperatives (Kopdes). Development economics expert from the Faculty of Economics and Business, Universitas Gadjah Mada (FEB UGM), Amirullah Setya Hardi, S.E., Cand.Oecon., Ph.D., highlighted the need to demonstrate the economic benefits and properly manage the risks associated with the proposed change in the salary disbursement mechanism.
He noted that the proposal could provide opportunities for Kopdes to grow and take on a greater role in financial services. However, the government needs to clearly explain the rationale for changing the existing payment mechanism, which has long operated through the banking system.
“Currently, salaries are paid directly to recipients. Government funds are disbursed through banking services, such as Regional Development Banks (BPD), and then transferred directly to civil servants as recipients,” he said.
Kopdes as a Financial Services Partner
Amirullah explained that Kopdes could be considered a partner in the existing financial services ecosystem, rather than a replacement for banks as the primary channel for salary disbursement.
He cited Laku Pandai, or Branchless Financial Services for Financial Inclusion, a program introduced by the Financial Services Authority (OJK) in 2015. The program enables banks to reach communities through financial service agents, including those in rural areas.
One example is BRILink, which provides banking services through agents, allowing people to conduct certain transactions without visiting a bank branch.
“If Kopdes partners with BRILink, for example, it would essentially only increase the number of outlets. There may be some benefits, but I do not think it would create something genuinely new in financial services,” he explained.
The Rights of Civil Servants and Retirees Must Be Guaranteed
Amirullah also emphasized that salary disbursement must ensure the rights of civil servants and retirees, particularly regarding the amounts received and the timeliness of payments. Any change in the mechanism should not result in reduced payments or delays in salary disbursement.
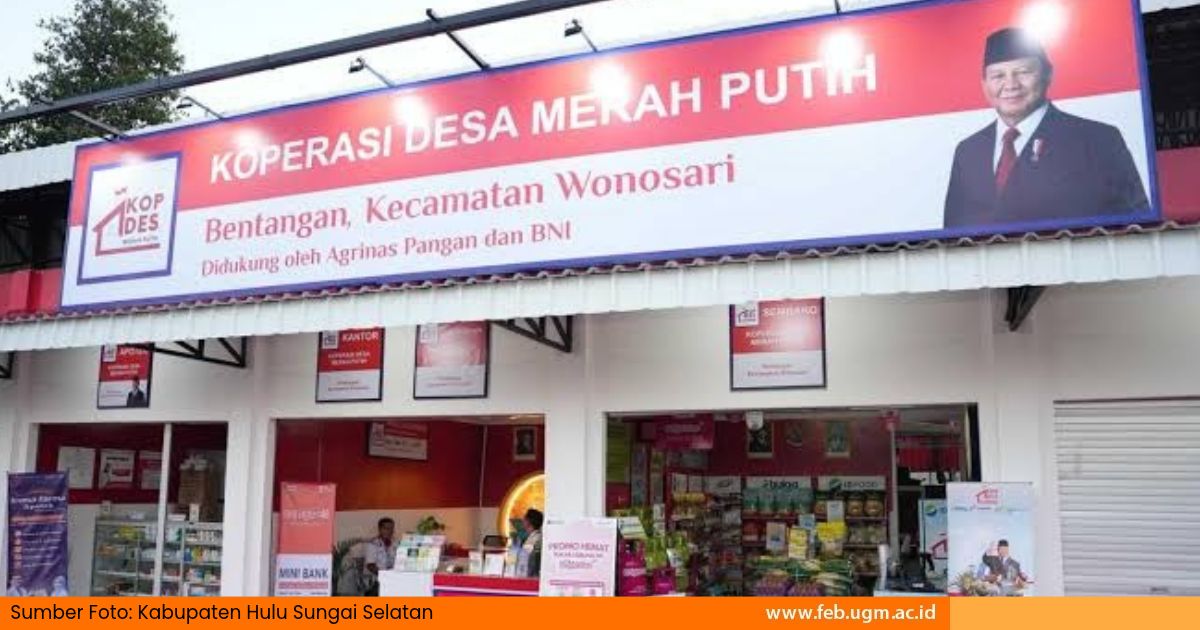
“It must be ensured that this scheme does not reduce the amount received or cause payment delays. If it subsequently generates additional benefits, then that would certainly be welcome,” he added.
Amirullah noted that the existing banking system already has relatively well-established service infrastructure. Therefore, if Kopdes is given greater responsibility, the government needs to consider the investment required in transaction systems, security, and institutional capacity.
He encouraged the government to conduct a thorough assessment and coordinate with relevant ministries, local governments, OJK, and other stakeholders before implementing the scheme. According to him, a pilot project is necessary to test the policy’s feasibility and effectiveness.
Institutional Risks
Another FEB UGM development economics expert, Dr. Evi Noor Afifah, S.E., M.S.E., also highlighted concerns regarding institutional readiness, governance, and financial literacy within village cooperatives, which have yet to be fully tested. According to her, salary disbursement is a sensitive financial service because it directly involves income used to meet people’s daily needs.
“There are at least three major risks of concern: operational and transaction security risks, governance and conflicts of interest, and systemic risks to public trust in the event of payment failures,” she said.
According to Evi, the success of financial inclusion cannot be measured merely by the number of transactions shifted to cooperatives. Financial services must provide access that is secure, affordable, and reliable.
Impact on MSMEs
Evi said that involving Kopdes would not automatically generate a multiplier effect for micro, small, and medium enterprises (MSMEs). A multiplier effect would only emerge if the policy successfully increases local spending, strengthens MSME supply chains, creates employment, and improves business productivity.
“The government needs to distinguish between an increase in transactions through Kopdes and the creation of new economic activity in rural areas. The policy’s impact must be demonstrated through credible evaluation showing that it generates additional turnover, added value, and employment opportunities compared with conditions without the policy,” she explained.
Pilot Project Before Implementation
Evi emphasized the importance of strengthening the professionalism of cooperative managers, transparency, managerial capacity, and accountability before Kopdes is entrusted with greater responsibilities. According to her, public policy should be developed based on problem analysis and evidence while taking into account economic rationale, institutional risks, and efficiency.
“Therefore, the government must first improve the quality and governance of Kopdes. Avoid building major ambitions on an institutional foundation that is not yet solid, particularly when the benefits remain unclear, and the potential risks of failure would have to be borne by many parties,” she said.
She proposed testing the scheme through pilot projects in disadvantaged, frontier, and outermost (3T) regions, particularly in areas facing high transportation costs, limited digital connectivity, and restricted access to financial services.
The pilot projects could be used to assess whether Kopdes can genuinely reduce costs and improve access to financial services for civil servants and retirees. The evaluation should cover costs borne by recipients, payment timeliness, transaction security, service reliability, and the impact on MSME turnover, economic value added, and job creation.
According to Evi, public policy must be grounded in problem analysis and evidence while considering economic rationale, institutional risks, and efficiency. Therefore, Kopdes’ involvement in financial services should be designed based on actual needs and institutional readiness, so that communities can realize its benefits without compromising security or the rights of salary recipients.
“Before implementing this scheme, the government must demonstrate that it is more efficient, safer, and more beneficial than the existing system,” she concluded.
Reportage: Shofi Hawa Anjani
Sustainable Development Goals